Does applying for a credit card hurt your credit score?

Quick insights
- A hard credit check from a credit card application may temporarily lower your credit score by a few points.
- Spacing out your applications may help minimize the impact on your credit profile.
- You can use free tools to monitor your credit score and track any fluctuations over time.
When you apply for a new credit card, lenders typically perform a hard credit check to review your financial history. This standard process helps them assess your creditworthiness, but it can also cause a slight dip in your credit score. Let's break down how applying for a credit card may impact your credit and what you can do to help manage it.
How applying for a credit card may affect your credit score
When you submit a credit card application, the lender typically requests a copy of your credit report from one or more of the major credit bureaus: Experian™, Equifax® and TransUnion®. This request is known as a hard credit check.
A hard credit check is a common part of the application process. It allows lenders to review your credit history and assess your creditworthiness. Because it indicates you're actively seeking new credit, a hard credit check is recorded on your credit report and may temporarily lower your credit score.
In contrast, a soft credit check happens when you check your own credit or when a lender reviews your profile to see if you are eligible to apply for an offer. Soft credit checks generally don't affect your credit score.
How many points could your credit score drop?
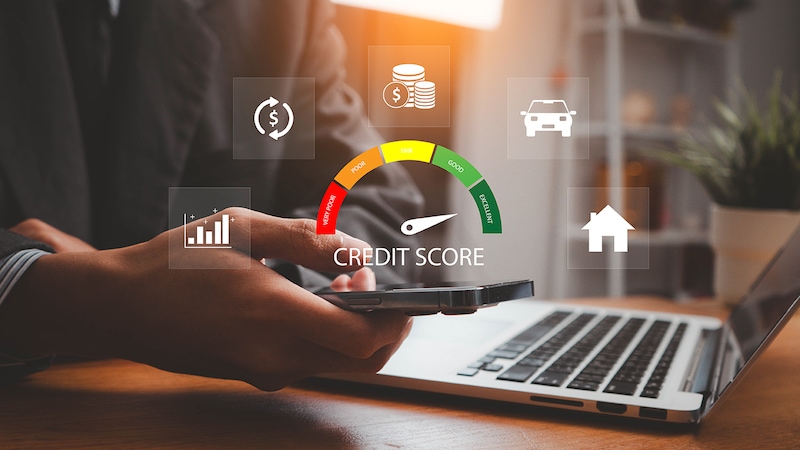
You might be relieved to learn that a single credit card application typically has a small impact on your credit score. Credit scoring models, such as VantageScore® and FICO®, consider several factors when calculating your score.
While a hard credit check is one of these factors, it usually plays a minor role compared to your payment history and the amount of credit you are currently using.
The slight drop from a hard credit check is usually temporary. If you continue to practice positive credit habits, such as paying your bills on time to avoid late fees and keeping your balances low, your score may recover over time.
Does getting denied for a credit card hurt your credit?
If your credit card application is unsuccessful, you might question whether the denial itself will further damage your credit. Fortunately, a credit card denial is not recorded on your credit report and doesn't directly impact your credit score.
However, the hard credit check from the application will still appear on your report and may cause a slight, temporary drop in your score. If you're not approved for a card, it may be helpful to review the lender's explanation and focus on building your credit before applying again.
How a new credit card could help your credit
While the initial application may cause a small dip in your score, opening and responsibly using a new credit card could potentially help improve your credit over time.
Here are a few ways a new card might benefit your credit profile:
- Increasing your available credit: A new credit card adds to your total available credit. If you keep your balances low, this may improve your credit utilization ratio, which is a key factor in your credit score.
- Building your payment history: Consistently making on-time payments on your new card can help build a positive payment history. Payment history is typically the most significant factor in calculating your credit score.
- Adding to your depth of credit: Having a mix of different credit accounts may positively influence your score. A new credit card can contribute to overall depth of credit.
Ways to minimize the impact of hard credit checks
While you typically cannot completely avoid hard credit checks when applying for new credit, you might be able to take steps to manage their impact on your credit profile.
Here are some strategies you might consider before applying:
- Spacing out your applications: Unlike installment loans where multiple credit checks may be consolidated, each credit card application counts as a separate hard credit check. Applying for multiple credit cards in a short period can signal to lenders that you are taking on too much debt. It may be helpful to wait some time between applications.
- Checking for preapproved offers: Many lenders allow you to see if you are eligible to apply for a card using a soft credit check. This may help you gauge your chances before submitting a formal application.
- Reviewing your credit report: Before applying, you may want to check your credit report for accuracy. Ensuring your information is correct may help you understand where your credit stands.
Tracking your credit score over time
Keeping an eye on your credit score may help you understand how your financial decisions, including new credit card applications, affect your overall credit health.
To help do this, you might consider enrolling in any credit monitoring tools offered by your bank or credit union. For example, Chase Credit Journey®, powered by Experian™, is a free online tool available to both Chase and non-Chase customers. It is designed to help customers better understand and manage their credit score and credit goals. Customers can access their credit score anytime with no impact to their credit, receive credit tips to help improve their score, and get identity monitoring—all in one place and for free.
Regularly checking your score may provide insights into your credit habits and help you stay informed about your progress.
In conclusion
Applying for a new credit card usually involves a hard credit check, which can temporarily lower your credit score. However, the impact is typically small and short-lived. By spacing out your applications and monitoring your progress, you might be able to help maintain your credit health while exploring new financial options.