Understanding credit utilization
Quick insights
- Credit utilization is the percentage of available credit you’re using at any given time.
- Having a credit utilization below 30% is generally viewed as favorable.
- Potential ways to lower your credit utilization include making frequent payments or opening another line of credit.
You've just been approved for a credit card and now you can begin making purchases—how exciting! Credit cards enable cardmembers to purchase items now and pay them off over time. Your new credit card might also provide opportunities to earn rewards or cash back.
However, because it can be easy to pay with your credit card, you could accumulate a balance subject to interest and fees.
Credit card management, including payment history and credit utilization ratio, may impact your credit score over time.
In this article, we’ll discuss what credit utilization is, ways it may affect your credit score and potential ways to lower your credit utilization.
What is credit utilization?
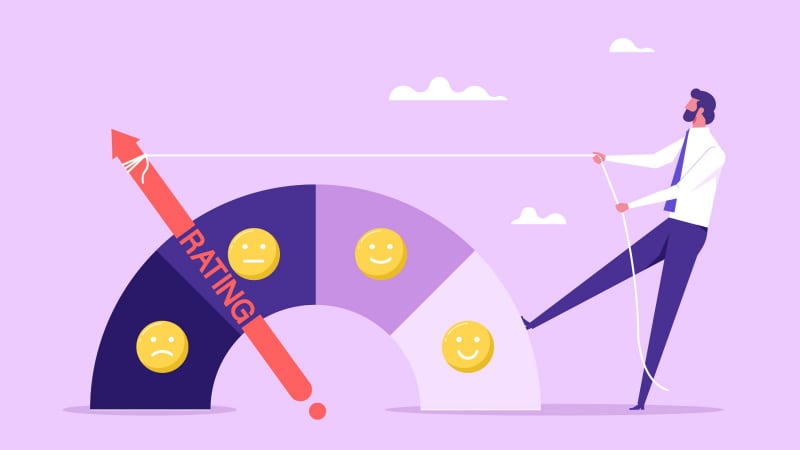
Credit utilization is one of several factors that may be considered when calculating your credit score. Credit utilization is the percentage of available credit you’re using at any given time.
Credit utilization ratio is the amount of credit you use against your total available credit, which may be lowered by paying down existing debts and balances. A credit utilization ratio of 30% or below is generally considered favorable.
Credit utilization accounts for about 20% of your VantageScore and 30% of your FICO® score.
As you get closer to your credit limit, you're increasing your ratio and potentially impacting your credit score.
When you enroll in Chase Credit Journey®, you'll learn more about how your credit utilization ratio may be considered, along with other factors, in calculating your free VantageScore3.0®.
Ways credit utilization matters to credit scoring
Having a lower utilization ratio is often an indicator of creditworthiness. It may signal to card issuers and lenders that you can responsibility manage your credit. Additionally, lenders may provide more favorable rates to those with a lower credit utilization.
Strategies to help lower credit utilization over time
Now that you know how important it is to maintain a low credit utilization ratio, you may be wondering how you can lower it. Maybe you've realized your current ratio is closer to 60% or 80%. There are steps you can take to help lower your credit utilization ratio. Let's dive into these below.
Making frequent payments
One strategy designed to help lower your credit utilization is to make frequent payments. A feature to having a credit card is that you can take home your purchase and wait to pay your bill at the end of its billing cycle (usually at the end of the month).
Paying off your purchases as you make them or making two payments towards your credit card bill in a month can help lower your credit utilization ratio because it reduces the amount you owe. The less you owe toward your credit card, the lower the credit utilization percentage. While this may not reflect immediately in your score, over time you could see a positive shift.
Requesting a credit limit increase
Another strategy designed to help is increasing your credit limit. You can contact your issuer to request an increased credit limit.
Taking this step can help lower your ratio, especially if your spending remains at a similar level. Because you have more room to spend with a higher credit limit, the amount owed will have less of an impact and lower your ratio.
You also may be able to increase your credit limit by opening a new credit card. While this may minimally hurt your score initially, an additional credit card provides more available credit.
Accessing your score with Chase Credit Journey
Your credit utilization ratio is just one of many factors when it comes to generating your credit score. While lowering your credit utilization does not happen overnight, there are strategies to begin improving how you use and understand the credit available to you.
One way to do this is by enrolling in Chase Credit Journey. Chase Credit Journey®, powered by Experian™, is a free online tool available to both Chase and non-Chase customers. It is designed to help customers better understand and manage their credit score and credit goals. Customers can access their credit score anytime with no impact to their credit, receive credit tips to help improve their score, and get identity monitoring—all in one place and for free.