Do you need insurance before buying a car?

Quick insights
- Most states require you to carry a minimum amount of liability coverage before you can legally drive a vehicle off a dealership lot.
- If you are financing the purchase, your lender will typically require you to show proof of an active policy before finalizing the loan.
- If you already have an active policy on another vehicle, your insurer may extend a grace period of 7 to 30 days to add the new car to your existing coverage, but this should be verified with the insurance company.
When you buy a car, having insurance is typically a legal requirement before you can drive off the lot. Both state laws and lender requirements mean you need to have coverage in place before completing your purchase. Learning how to secure a policy may help you streamline the buying process.
Do you need insurance to buy a car?
In most states, you need to have auto insurance before you can legally operate a vehicle on public roads. Because of this, dealerships will typically ask for proof of coverage before handing over the keys. If you are financing the vehicle through a bank, the lender will also require you to provide proof of an active policy before they finalize the loan agreement. The lender needs to verify that their collateral is protected in the event of an accident or theft.
If you are purchasing a vehicle from a private seller, you may be able to complete the transaction without showing proof of coverage. However, you still need to obtain a policy before you can register the vehicle or legally drive it. Driving without coverage is illegal in most states and can result in fines, license suspension or vehicle impoundment.
How to get insurance before buying a car
You may be able to get a policy before your purchase if you prepare in advance.
- Gather vehicle information: To get a quote, you typically need the year, make and model of the vehicle you plan to purchase. If you have already selected a specific car, having the vehicle identification number (VIN) can help the insurer provide a quote.
- Compare quotes: You can request quotes from multiple carriers to find a policy that fits your budget. Comparing rates from several providers may help you identify a plan that meets your needs.
- Choose your coverage: Select a policy that meets your state minimum requirements and any additional conditions set by your lender. If you are financing the vehicle, the lender may require collision and comprehensive coverage in addition to liability protection.
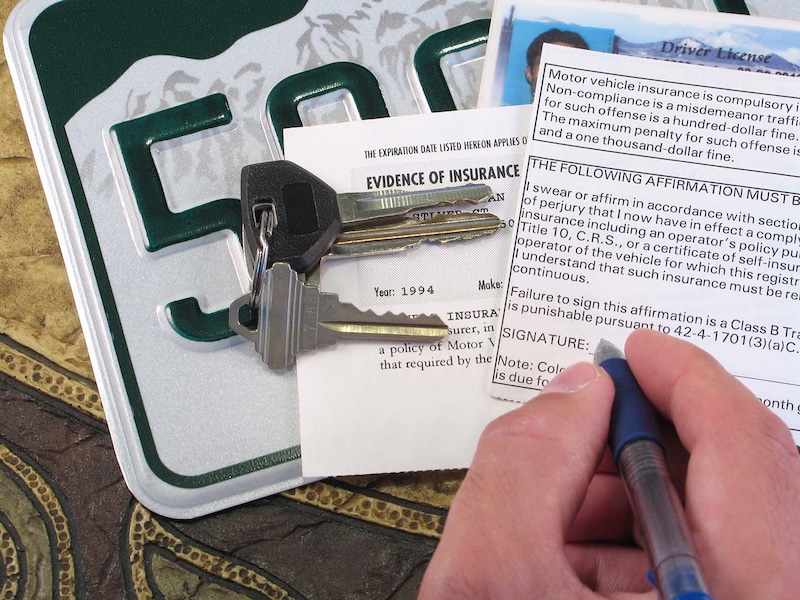
- Provide proof: Once you purchase a policy, the insurer will issue a digital or physical insurance ID card. You can present this document to the dealership and your lender to help satisfy their requirements.
When to get insurance when buying a car
The timing of when you need to secure coverage depends on your current situation. If you already have an active auto policy on another vehicle, your insurer may extend a grace period that temporarily covers the new purchase. This grace period typically ranges from 7 to 30 days, during which the new vehicle carries the same level of coverage as your existing policy. You should contact your insurer to confirm the length of the grace period and add the new vehicle to your policy before the window expires.
If you are a first-time buyer or do not have an existing policy, there is no grace period. You need to purchase a policy and have it active before you can drive the vehicle off the lot. In this situation, you can shop for quotes and purchase a policy before you arrive at the dealership. Some insurers allow you to complete the application and activate coverage the same day.
What insurance coverage do you need when buying a car?
The type of coverage you need depends on how you are paying for the vehicle and where you live. Below are a few types:
- Liability coverage: Most states require you to carry a minimum amount of liability insurance to cover injuries or property damage you may cause to others. This coverage is a legal requirement in most states before you can register or drive the vehicle.
- Collision coverage: If you are financing the vehicle, your lender will typically require collision coverage. This coverage pays for damage to your vehicle resulting from a collision with another vehicle or object.
- Comprehensive coverage: Lenders also generally require comprehensive coverage, which pays for damage caused by events such as theft, vandalism or weather. Together with collision coverage, this is often referred to as full coverage.
The bottom line
You generally need to have an active insurance policy in place before you can drive legally. If you are financing the purchase, your lender will require proof of coverage before finalizing the loan. By gathering vehicle information, comparing quotes and selecting the right coverage in advance, you can help streamline the purchasing process.