How to accept credit card payments: A guide and checklist for small businesses
Presented by Chase Payment Solutions®

Key takeaways
- Accepting credit card payments can help support small business growth by offering customers convenient payment options.
- Businesses can process credit card payments in person, online, over the phone or by sending invoices.
- Understanding payment processing, common fees and key security measures can help you choose a credit card payment solution.
Accepting credit card payments can represent a milestone for small businesses aiming to broaden their customer base and adjust to evolving payment trends. Whether you are transitioning from cash-only or launching your first business, knowing your options can help you deliver a smooth checkout experience for your customers.
In this article, we’ll discuss ways to accept credit card payments and some considerations when choosing a payment system for your business.
Benefits of accepting credit card payments
Credit card payments are a standard part of both in-store and online shopping experiences. Many shoppers expect to be able to pay by card.
Additionally, card payments typically provide quicker access to funds for businesses, as payment processors generally deposit proceeds into your bank account within 1-2 business days, supporting smoother cash flow. Security features from payment providers may also offer protection for both merchants and customers against suspicious transactions.
How to take credit card payments
To start accepting credit cards — whether you're swiping cards at a physical storefront or taking orders through your website — you need a way to process the transaction and receive the funds. This typically means businesses need a payment processor, hardware or software to enable transactions and a business bank account to receive funds.
Businesses will also need merchant account access, which often means having a merchant account and a merchant service provider (MSP):
- Merchant account: A merchant account is a specialized bank account that temporarily holds your funds from credit card sales before they are transferred to your main business account.
- Merchant service provider: An MSP provides the necessary technology, such as point-of-sale (POS) terminals or online payment gateways, needed to process the sale.
While you can piece these different services together, many businesses prefer an all-in-one solution. Some providers offer both the processing technology and the merchant account in one package, which can make it easier to manage your cash flow and daily operations from a single dashboard.
Common credit card processing fees
As you evaluate providers, it’s helpful to understand common merchant fees associated with processing payments. While rates vary by provider and business type, certain fees are fairly standard:
- Interchange fees: This is the largest portion of the processing cost, paid to the card-issuing bank for each transaction. It is usually a percentage of the sale plus a small flat fee.
- Assessment fees: A smaller, separate fee paid directly to the credit card networks (like Visa® or Mastercard®) for the ability to accept their cards.
- Chargeback fees: A penalty fee incurred if a customer disputes a charge, and the bank reverses the transaction.
Keeping payment data secure with PCI compliance
As you set up your payment system, you will also need to ensure Payment Card Industry Data Security Standard (PCI) compliance. PCI compliance refers to a set of industry standards designed to ensure that your business processes, stores and transmits credit card information securely.
Partnering with a reputable, established payment processor can help make PCI compliance easier to implement and maintain.
Ways to accept credit card payments
Small businesses can choose from several methods to accept credit card payments, depending on their business type, where they sell and what their customers prefer. Payments are typically accepted in person, online or over the phone, and can even be recurring.
Accepting credit card payments in person
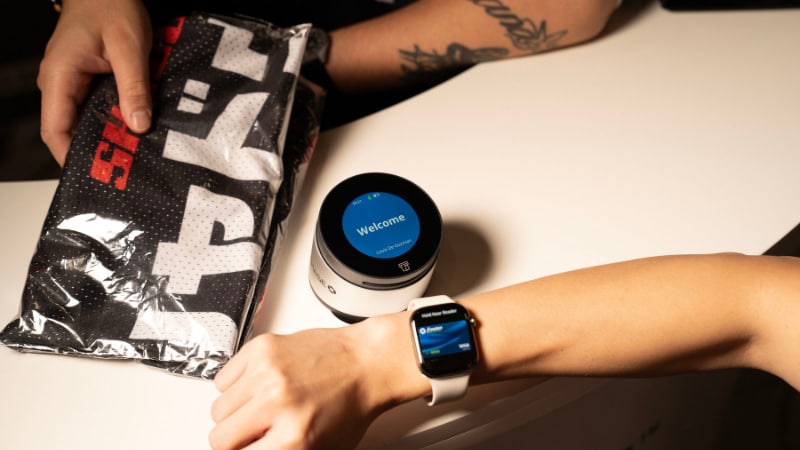
Physical stores, mobile vendors and in-person service providers can process credit card payments using a countertop terminal or a portable wireless terminal that allows you to take payments on the go. A terminal that can process payments by chip, swipe, tap to pay or contactless cards can provide flexibility and options for your customers.
Many in-person solutions include compact mobile card readers that connect to a smartphone or tablet, which may enable you to take payments wherever you operate. These readers can be a good fit for food trucks, market stalls, mobile professionals and any business without a fixed location.
Accepting credit card payments online
Accepting online credit card payments typically involves setting up a payment gateway on your website so customers can safely enter their card details at checkout. Checkout will likely happen at a virtual storefront, which might be your website or a shop on an external site.
Online payments often require:
- A payment gateway, where the customer inputs their payment information
- A payment processor, which collects payment information and coordinates with credit card networks, issuing banks and receiving banks to transfer the funds
If your payment processor does not include merchant account capabilities, you may also need to open a merchant account to accept online payments.
Accepting credit card payments over the phone
Certain clients may want to pay over the phone, which can be common for specialized services or custom orders. In this instance, you will likely need to manually enter payment details into a POS or virtual terminal. A virtual terminal is a web-based version of a physical card reader.
If you manually enter payment details for transactions, a PCI-compliant payment processor can help enforce security protocols. Following other best practices, such as avoiding writing down customer information, can also help keep payment information secure.
Accepting recurring payments
For service providers, freelancers and B2B businesses that require regular payment collection, digital invoicing tools can enable you to send invoices with embedded payment links, which lets customers pay securely by card.
Automated billing features can handle subscriptions, memberships or repeat services, which may help streamline your workflow and accelerate payment collections.
Considerations when choosing card payment methods
Selecting an effective way to accept credit card payments for your small business may mean weighing several factors, including:
- Business model and industry: Your business type often shapes your payment needs. Retailers may need a fixed terminal, while mobile services might favor a portable card reader.
- Sales channels: If you sell both in person and online, you may want to look for a unified solution that manages all your payments together. If you only sell on the go, you might consider choosing a system that prioritizes mobility.
- Transaction volume: Higher sales volumes may unlock better rates or features with some providers. For limited monthly activity, you might seek options without minimums or long-term commitments.
- Hardware and software needs: Consider whether you need a physical terminal, a mobile reader or a virtual terminal. Some systems also include inventory control, sales reports and customer insights.
- Security and compliance: You may want to look for advanced security measures, including encryption, tokenization, EMV chip support and PCI compliance features to help keep payment data secure.
- Invoicing and payment links: If you send invoices or want to receive payments without a website or terminal, you might opt for a provider that supports digital invoices or payment links.
- Customer experience: Fast, reliable and easy-to-use payment tools can help you make a strong impression and potentially encourage repeat purchases.
Checklist: Getting started with credit card payments
Before processing credit card payments, you may want to consider these steps:
- Define your needs: Consider whether you'll accept payments in person, online, by phone or via invoice (or a combination of multiple methods) based on your business and customers.
- Integrated features: Some options offer integrated customer insights or accounting features.
- Research providers: You can evaluate payment processors for their fees, contracts, hardware options, integrations and user feedback.
- Understand fees: It can be helpful to carefully assess all costs, including per-transaction charges, monthly or yearly fees, setup expenses and extra features or equipment.
- Ensure security: You might consider choosing a provider with strong security features, PCI compliance measures and EMV chip capabilities.
- Set up your system: You may need to install the necessary hardware or software, connect your solution to your website, if applicable, and test payments before launching.
- Train your team: It can be beneficial to ensure your staff is familiar with the new tools and knows how to handle customer questions about payments.
- Monitor and review: You may want to regularly check your payment activity, monitor for suspicious transactions and use provider reports to help improve your business operations.
In summary
Accepting credit card payments may help your business attract more customers. With the right solution, businesses can process payments in person, online, over the phone or via invoice. Taking the time to review your needs and options can help you select a payment system that suits your objectives and may contribute to your long-term success.
To sign up for Chase Payment Solutions, reach out to a Payments Advisor at 1-877-843-5690 or connect with us here.