The blue wave is changing the AI trade

The U.S. economy and the stock market have proven resilient in 2026 even in the face of higher interest rates, geopolitical volatility and yet another energy shock. While the U.S. consumer, aided by fiscal stimulus and tax cuts, is still spending, a growing driver of GDP growth is the artificial intelligence (AI) buildout.
In the 2026 U.S. midterm elections, the Democratic Party gained control of both the House of Representatives and the U.S. Senate, setting the stage for gridlock with a Republican president – especially when it comes to the continued development and adoption of AI across the country. Investors feared a federal moratorium that mirrors some of the state-led initiatives to curb the buildout, in response to affordability and zoning concerns. It’s only natural that the outcome of the elections initially sent stock market futures plunging nearly 2% before rebounding with significant volatility in technology companies even days after the result.
AI buildout still in play
Democratic gains increase the likelihood of tougher scrutiny around data center development, electricity affordability and who pays for new grid infrastructure. This can create near-term uncertainty for sectors that trade in line with AI developments like utilities – especially those with exposure to fast-growing markets like Texas and Georgia that offer affordable land, labor and both energy and water access. Even as investors reprice that risk, the structural backdrop remains in place. Hyperscaler investment is expected to continue. Electrification and the grid buildout are still pressing needs to support higher power demand and capital spending.
Stopping the data center buildout is still a tall order. Initial efforts to curb the data center buildout began over the summer. Any new policies to slow or restrict new connections would build on a process that’s already underway. More notable policy changes could be around who bears the costs of additional grid connections, changes to tax exemptions, stricter financial commitments and emergency curtailment requirements, among others. While much of this uncertainty was priced in leading into the elections, the magnitude of the Democratic gains was not. And that’s changing the nature of the tech trade underneath the hood.
Ready to take the next step in investing?
We offer $0 commission online trades, intuitive investing tools and a range of advisor services, so you can take control of your financial future.
A different kind of moat
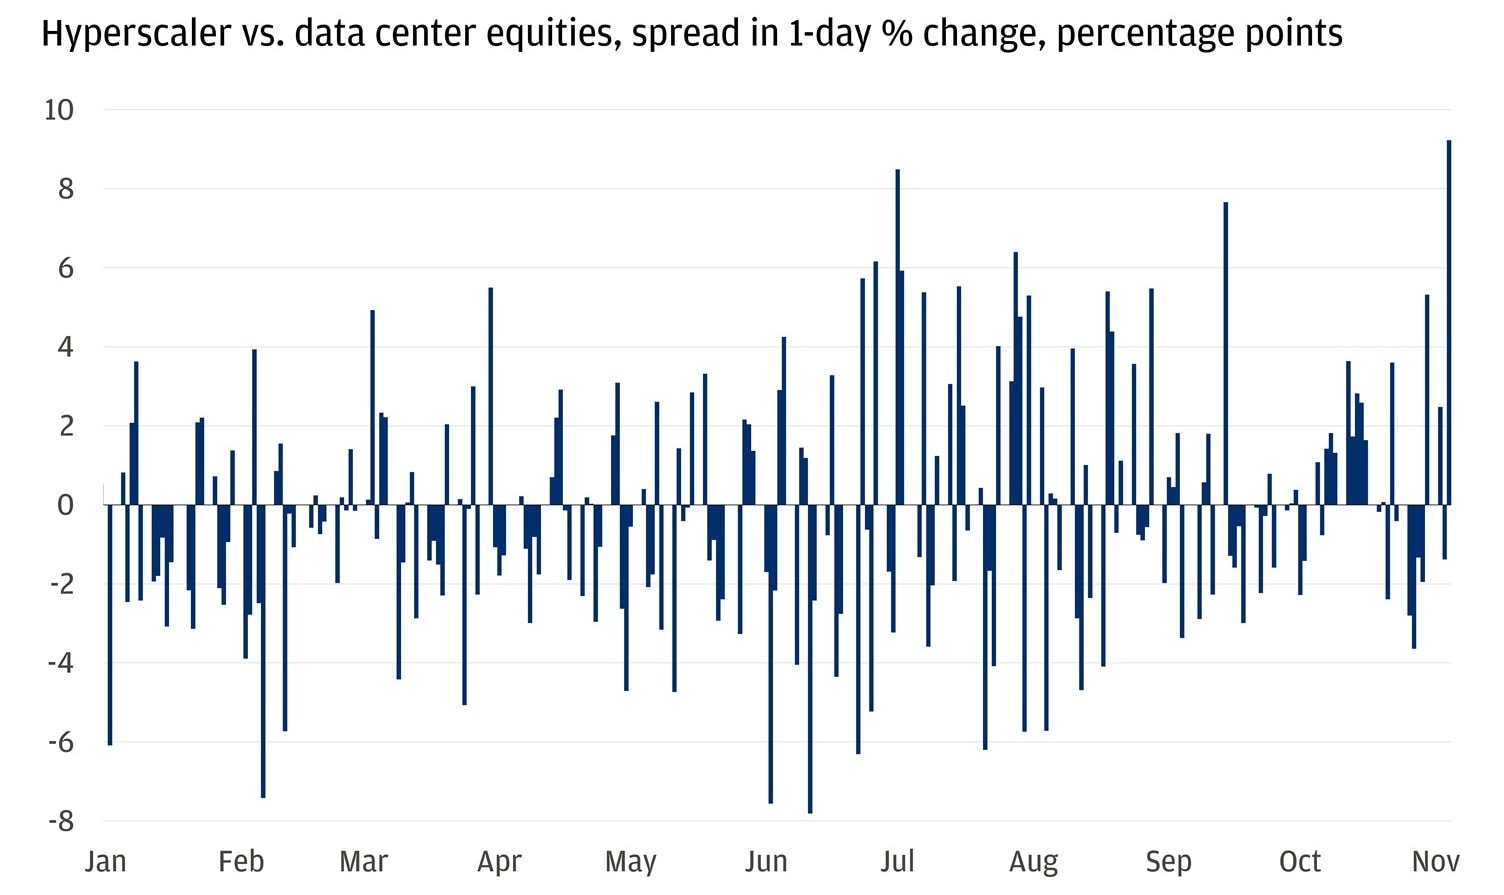
In an environment where regulation could change even in the most AI-friendly states, companies with existing compute and data center projects – like the hyperscalers – have the edge. Plus, additional regulatory proposals target new developments, not existing ones. That could strengthen the position of companies with operational data centers, secured power and established customers. Combined with any potential moderation in AI growth and the ability to meet greater construction and permitting standards, the established lead that some of the biggest tech companies have is even more beneficial relative to the parts of the tech trade that rely on the incremental buildout.
And that’s something investors are already pricing, sending the message that owning productive capacity today is different from depending on its construction tomorrow – even if that means factoring in potential regulatory risk.
Hyperscalers may have an edge post-election
Pain in ‘picks and shovels’
Before the policy details have even been settled, or formally proposed, investors have already repriced these possibilities. It’s most visible in parts of the “picks and shovels” AI infrastructure trade – the part of the market that rallied on the certainty of the buildout even as the return on investment remains in question.
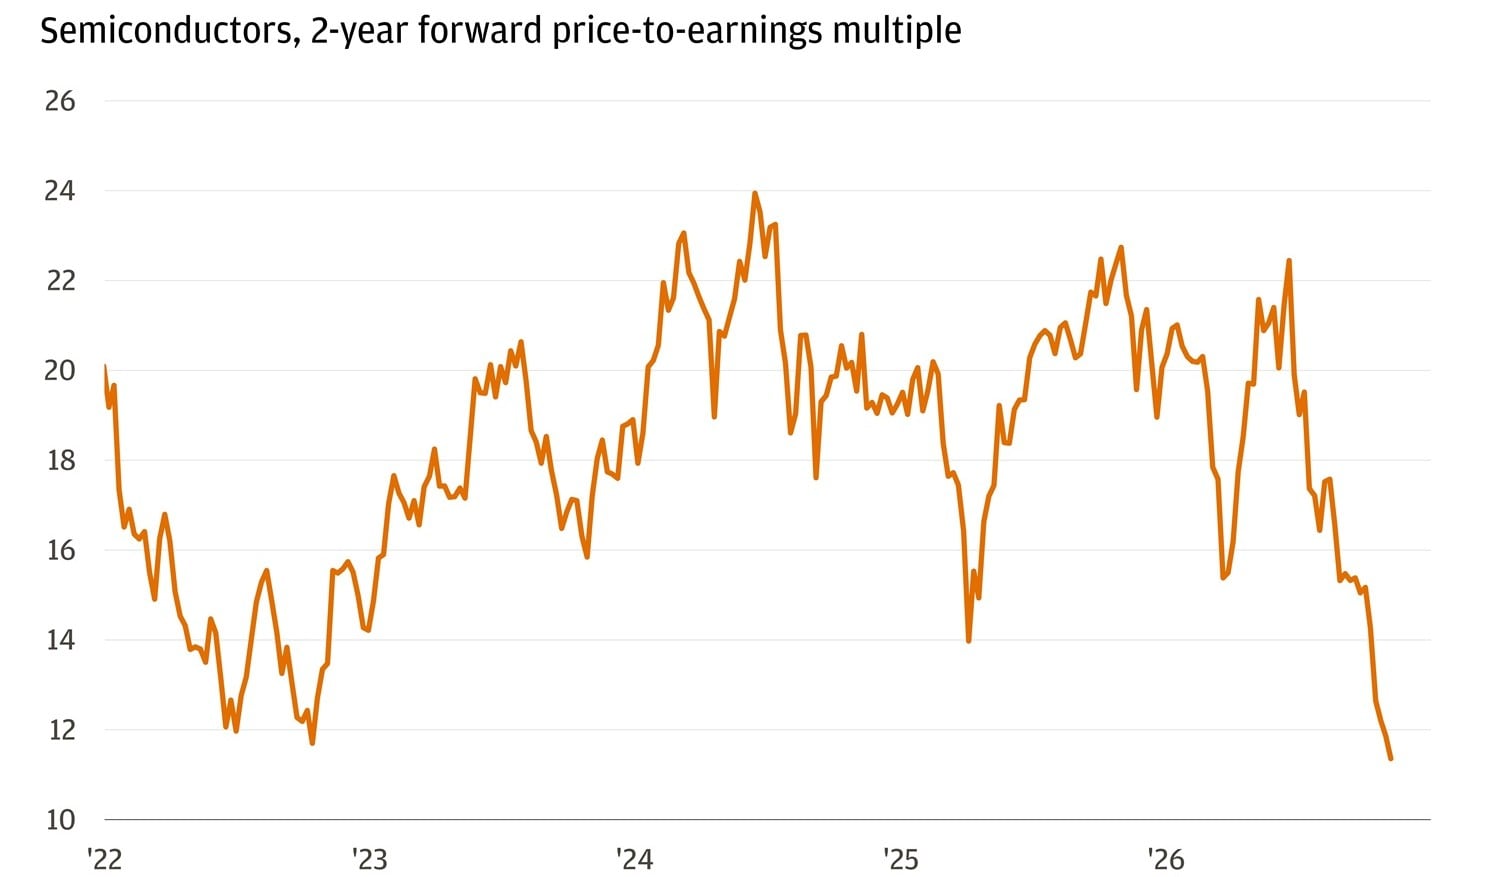
The 24-month forward price-to-earnings ratio of the MVIS US Listed Semiconductor 25 Index has halved since June. After trading at a peak of 22.5 times forward earnings in June, the index currently trades at 11.4 times forward earnings. That’s at a valuation lower than when investors were digesting the beginning of the conflict in Iran, “Liberation Day” and the stock market lows of 2022. It reflects a market questioning the durability of the industry’s earnings and continued growth in capital expenditures.
Chip valuations have fallen to their lowest levels in years
But that’s where the opportunity may lie. Yes, regulation is subject to change, but the scale of economic growth that has come from this sector alone may bear some impact on the level and willingness to limit continued development.
The AI trade is far from over, but it is evolving. Financing, regulatory and power constraints can mean a bumpy road ahead, but unless end demand falters, the risk of an inventory overhang and earnings slowdown may already be baked into valuations. As the structural backdrop of the AI buildout remains in place, the key is to determine which companies have the lead in an undeniable technological evolution that can broaden out in the years to come.
All market and economic data as of 11/05/2026 are sourced from Bloomberg Finance L.P. and FactSet unless otherwise stated.
You're invited to subscribe to our newsletters
We'll send you the latest market news, investing insights and more when you subscribe to our newsletters.