
Enjoy tax-deferred growth with a Traditional IRA
A J.P. Morgan Individual Retirement Account (IRA) offers a strategic way to save for retirement. Contributions to your Traditional IRA may be tax-deductible, and earnings, if any, grow tax-deferred.
The basics of a Traditional IRA
What is a Traditional IRA?
A Traditional IRA is an individual retirement account in which your contributions may be tax-deductible. Your earnings, if any, are tax-deferred and will be included in your taxable income at the time of withdrawal.
Who is a Traditional IRA for?
Anyone with taxable compensation can open a Traditional IRA. Your contributions may be fully or partially deductible, depending on your filing status and income.
Why invest in a Traditional IRA?
A key advantage of a Traditional IRA is the potential ability to reduce your taxable income as you save for retirement. Generally, your Traditional IRA earnings won’t be taxed until you take a distribution from your IRA.
Benefits of a Traditional IRA with J.P. Morgan

Bring it all together
Roll over and consolidate eligible 401(k)s and other retirement accounts into one IRA—so you can simplify your finances and view your full retirement picture in one place on the Chase Mobile® app or at chase.com.

Personalized advice
Work with our J.P. Morgan advisors to help design a retirement strategy based on what’s important to you.

Powerful tools
From alerts to screeners, we make it easy to build diversified portfolios.

More investment options with J.P. Morgan
Most workplace plans offer a limited selection of funds. With a J.P. Morgan IRA, you can invest in 10,000+ stocks, ETFs, mutual funds and bonds.
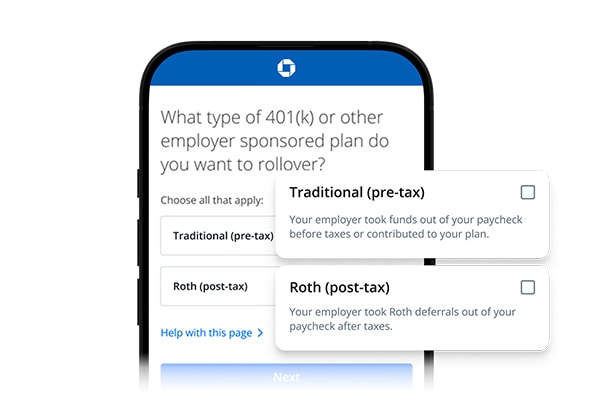
Thinking about rolling over your 401(k)?
We can help you move over a 401(k) or other eligible retirement accounts into a tax-advantaged individual retirement account (IRA).
Traditional IRA vs. Roth IRA
Traditional IRA | Roth IRA |
|---|---|
Who can contribute | |
To qualify, you or your spouse (if filing jointly) must have earned income | To qualify, you or your spouse (if filing jointly) must have earned income |
Annual income limits | |
None, but may affect tax deductibility (see Tax-Deductible Contributions) | Contributions might be limited based on filing status and income; refer to IRS website for applicable limits |
Main benefits | |
Contributions are generally tax-deductible, and earnings (if any) grow tax-deferred until withdrawn | Earnings (if any) grow tax-deferred and can be withdrawn exempt from federal taxes if it is a qualified distribution |
Annual contribution limit (2026) | |
The lesser of earned income or: $7,500 (under age 50), $8,600 (age 50 and over) | The lesser of earned income or: $7,500 (under age 50), $8,600 (age 50 and over) |
Tax-deductible contributions | |
Deductibility may be limited if you or your spouse are covered by a retirement plan at work and your income exceeds certain levels | Contributions are non-deductible; refer to IRS website for applicable limits |
Withdrawals | |
Deductible contributions and any earnings are taxed as ordinary income | Contributions can be withdrawn at any time without tax or IRS penalty; qualified distributions are exempt from federal taxes |
Required withdrawals | |
RMDs must begin by April 1 of the year following the year you turn 73; subsequent distributions by Dec 31 each year after turning 73; beneficiaries subject to RMD rules | None during your (original owner’s) lifetime; beneficiaries subject to RMD rules |
Investor considerations | |
Contributions may qualify for tax-deduction; you anticipate being in a lower tax bracket in retirement | There are income requirements for contribution eligibility; you anticipate being in a higher tax bracket in retirement |
Earn up to $1,000 when you open and fund an online investing account
Get rewarded when you open and fund a J.P. Morgan Self-Directed Investing account by transferring cash or investments from an eligible external account—including rolling over a 401(k) or other retirement account.
Offer expires 01/21/2027.
Retirement tools and resources
Retirement calculators
Run your numbers with our calculators to see how your current plan is working toward your goals.
Investing insights
You deserve a great retirement. We'll help you plan today so you're ready for what's ahead.
Already have an IRA with J.P. Morgan?
Make a contribution
Make a one-time contribution or set up recurring transfers—from your Chase checking or savings accounts into your IRA.
Track your portfolio’s performance
Track and compare your portfolio’s performance relative to major indices, including the Consumer Price Index to measure against inflation.
Frequently asked questions about Traditional IRAs
A Traditional IRA is a retirement account where your contributions may either be tax-deductible or non-deductible, and your earnings and any previously deducted contributions will be included in your taxable income when you withdraw your money.
Traditional IRA contributions may be tax-deductible for the year for which they are made. Deductibility for a Traditional IRA contribution may be limited based on your income tax filing status, if your modified adjusted gross income (or “MAGI”) exceeds certain levels, and if you or your spouse are covered by a workplace retirement plan.
The IRS sets annual contribution limits for Traditional IRAs and Roth IRAs. For 2026, the annual maximum is $7,500 if you are under the age of 50, or $8,600 if you are 50 or above. Learn moreOpens overlay.
While eligibility for a tax deduction is dependent on income and involvement in other employer plans, you can contribute at any age if you (or your spouse, if filing jointly) have taxable compensationOpens overlay.
You may withdraw from a Traditional IRA at any time; however, withdrawals from your Traditional IRA are includible in your taxable income and if you are under age 59 ½ you may have to pay an additional 10% tax for early withdrawal unless you qualify for an exception.
A rollover IRA is an IRA that is set up to accept assets from an employer-sponsored plan like a 401(k) or 403(b) once you have a qualifying distributable event (such as changing employers or retiring). The rollover IRA could be either a Traditional or Roth IRA depending on the circumstances.
Traditional IRAs
- Tax benefits: Contributions may be tax-deductible, which can reduce your taxable income for the tax year to which the contribution applies.
- Growth: Earnings grow tax-deferred, meaning you don't pay taxes on them until you withdraw.
- Withdrawals: Withdrawals are taxed as ordinary income. Required minimum distributions start at age 73. If you are under age 59 1/2 you may have to pay an additional 10% tax for early withdrawal.
Roth IRAs
- Tax benefits: Contributions are made with after-tax dollars and are not tax-deductible, but qualified distributions are tax-free.
- Growth: Earnings grow tax-free, providing potential tax-free income in retirement.
- Withdrawals: Contributions can be withdrawn anytime without penalties. There are no required minimum distributions, but if you are under age 59 ½ you may have to pay an additional 10% tax for early withdrawal.
You can easily open a Traditional IRA online or with a J.P. Morgan advisor. Once you fill out an application and are approved, you’re ready to start making contributions (if eligible) and investing in mutual funds, bonds, stocks and exchange-traded funds (ETFs).
Yes, you can have both a Traditional IRA and a Roth IRA and may contribute to one or both as long as you (or your spouse, if filing jointly) have earned income. Keep in mind that the annual IRA contribution limit is shared across all your IRAs combined (Traditional and Roth), and Roth contributions may be limited by income.
Required minimum distributions (RMDs) must begin by April 1 of the year after you turn 73. If you delay your first RMD until then, you’ll need to take two distributions that year—the first by April 1 and the second by December 31. Subsequent distributions must be taken by December 31 of each year thereafter. Beneficiaries are subject to RMD rules, including those with a beneficiary Roth IRA.
Yes, having a 401(k) doesn’t prevent IRA contributions if you (or your spouse, if filing jointly) have earned income. However, if you’re covered by a retirement plan at work, Traditional IRA tax deductibility may be limited based on income, and Roth IRA contributions may also be limited by income.
To open a Self-Directed Investing Traditional IRA, you need to be at least 18 years old and have a valid Social Security number and U.S. home address. We may also ask for your driver's license or state-issued ID. Apply now for a Self-Directed Investing account.
Looking to work with an advisor? Speak with our Retirement Specialists at 1-833-829-6472 Monday–Friday, 8 AM–9 PM ET and Saturday, 8:30 AM–5 PM ET.
Eligibility depends on factors such as earned income, age, filing status, and the type of IRA you’re considering. Use our calculator to check your eligibility.