
Enjoy tax-free growth potential with a Roth IRA
You can fund your Roth IRA with after-tax dollars, which grow tax-deferred. If certain conditions are met, you can make tax-free withdrawals.
The basics of a Roth IRA
What is a Roth IRA?
A Roth IRA is an individual retirement account in which your contributions are not tax-deductible. Your earnings, if any, are tax-deferred and may be withdrawn tax-free if certain conditions are met.
Who is a Roth IRA for?
Anyone with taxable compensation who wants to save for retirement on a potentially tax-free basis can open a Roth IRA. You cannot deduct contributions from a Roth IRA, and they may be limited based on your income tax filing status and modified adjusted gross income (MAGI).
Why invest in a Roth IRA?
Contributing to a Roth IRA is a way to save for retirement that may provide a tax advantage upon withdrawal. Contributions are made with after-tax dollars (and are never deductible), but qualified distributions aren't subject to federal tax upon withdrawal. Learn moreOpens overlay.
Benefits of a Roth IRA with J.P. Morgan

Bring it all together
Roll over and consolidate eligible 401(k)s and other retirement accounts into one IRA—so you can simplify your finances and view your full retirement picture in one place on the Chase Mobile® app or at chase.com.

Personalized advice
Work with our J.P. Morgan advisors to help design a retirement strategy based on what’s important to you.

Powerful tools
From alerts to screeners, we make it easy to build diversified portfolios.

More investment options with J.P. Morgan
Most workplace plans offer a limited selection of funds. With a J.P. Morgan IRA, you can invest in 10,000+ stocks, ETFs, mutual funds and bonds.
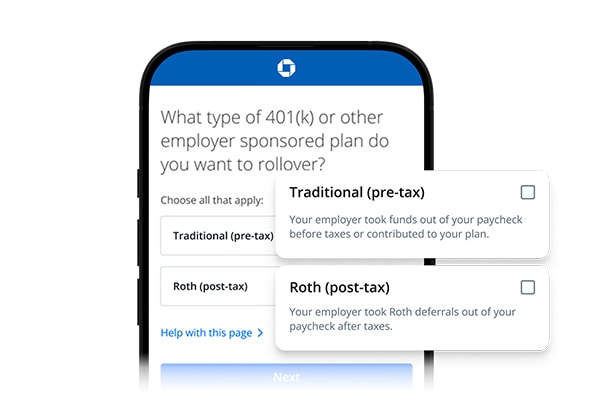
Thinking about rolling over your 401(k)?
We can help you move over a 401(k) or other eligible retirement accounts into a tax-advantaged individual retirement account (IRA).
Traditional IRA vs. Roth IRA
Traditional IRA | Roth IRA |
|---|---|
Who can contribute | |
To qualify, you or your spouse (if filing jointly) must have earned income | To qualify, you or your spouse (if filing jointly) must have earned income |
Annual income limits | |
None, but may affect tax deductibility (see Tax-Deductible Contributions) | Contributions might be limited based on filing status and income; refer to IRS website for applicable limits |
Main benefits | |
Contributions are generally tax-deductible, and earnings (if any) grow tax-deferred until withdrawn | Earnings (if any) grow tax-deferred and can be withdrawn exempt from federal taxes if it is a qualified distribution |
Annual contribution limit (2026) | |
The lesser of earned income or: $7,500 (under age 50), $8,600 (age 50 and over) | The lesser of earned income or: $7,500 (under age 50), $8,600 (age 50 and over) |
Tax-deductible contributions | |
Deductibility may be limited if you or your spouse are covered by a retirement plan at work and your income exceeds certain levels | Contributions are non-deductible; refer to IRS website for applicable limits |
Withdrawals | |
Deductible contributions and any earnings are taxed as ordinary income | Contributions can be withdrawn at any time without tax or IRS penalty; qualified distributions are exempt from federal taxes |
Required withdrawals | |
RMDs must begin by April 1 of the year following the year you turn 73; subsequent distributions by Dec 31 each year after turning 73; beneficiaries subject to RMD rules | None during your (original owner’s) lifetime; beneficiaries subject to RMD rules |
Investor considerations | |
Contributions may qualify for tax-deduction; you anticipate being in a lower tax bracket in retirement | There are income requirements for contribution eligibility; you anticipate being in a higher tax bracket in retirement |
Earn up to $1,000 when you open and fund an online investing account
Get rewarded when you open and fund a J.P. Morgan Self-Directed Investing account by transferring cash or investments from an eligible external account—including rolling over a 401(k) or other retirement account.
Offer expires 01/21/2027.
Retirement tools and resources
Retirement calculators
Run your numbers with our calculators to see how your current plan is working toward your goals.
Investing insights
You deserve a great retirement. We'll help you plan today so you're ready for what's ahead.
Is a Roth conversion right for you?
Use our calculator to see the potential future value of your Traditional IRA in comparison to a Roth IRA.
Already have an IRA with J.P. Morgan?
Make a contribution
Make a one-time contribution or set up recurring transfers—from your Chase checking or savings accounts into your IRA.
Track your portfolio’s performance
Track and compare your portfolio’s performance relative to major indices, including the Consumer Price Index to measure against inflation.
Frequently asked questions about Roth IRAs
A Roth IRA is a retirement account where you may be able to contribute after-tax dollars and you don’t have to pay federal tax on “qualified distributions” (as defined by the IRS). You cannot deduct contributions to a Roth IRA.
You can contribute at any age if you (or your spouse, if filing jointly) have taxable compensationOpens overlay and your modified adjusted gross income is below certain amountsOpens overlay.
The IRS sets annual contribution limits for Roth IRAs and Traditional IRAs. For 2026, the annual maximum is $7,500 if you are under the age of 50, or $8,600 if you are 50 or above. However, your Roth IRA contributions may be limited based on your income tax filing status and modified adjusted gross income. Learn moreOpens overlay.
You may withdraw from a Roth IRA at any time; however, earnings that you withdraw may be subject to taxes if they do not meet the IRS definition of a “qualified distribution,” and if you are under age 59 ½ you may have to pay an additional 10% tax for early withdrawal unless you qualify for an exception. On the other hand, you don’t have to pay federal tax on any “qualified distributions.” Note there are no required minimum distributions (RMDs) with a Roth IRA if you are the original owner.
A rollover IRA is an IRA that is set up to accept assets from an employer-sponsored plan like a 401(k) or 403(b) once you have a qualifying distributable event (such as changing employers or retiring). The rollover IRA could be either a Traditional or Roth IRA depending on the circumstances.
Traditional IRAs
- Tax benefits: Contributions may be tax-deductible, which can reduce your taxable income for the tax year to which the contribution applies.
- Growth: Earnings grow tax-deferred, meaning you don't pay taxes on them until you withdraw.
- Withdrawals: Withdrawals are taxed as ordinary income. Required minimum distributions start at age 73. If you are under age 59 1/2 you may have to pay an additional 10% tax for early withdrawal.
Roth IRAs
- Tax benefits: Contributions are made with after-tax dollars and are not tax-deductible, but qualified distributions are tax-free.
- Growth: Earnings grow tax-free, providing potential tax-free income in retirement.
- Withdrawals: Contributions can be withdrawn anytime without penalties. There are no required minimum distributions, but if you are under age 59 ½ you may have to pay an additional 10% tax for early withdrawal.
To convert a Traditional 401(k) to a Roth IRA, you’ll need to roll over your 401(k) to a Traditional IRA first, then convert it to a Roth.
To convert your J.P. Morgan Traditional IRA to a J.P. Morgan Roth IRA:
- Go to our Brokerage Forms page and choose the "Roth IRA Conversion Request" form.
- Complete the form and send it to the address provided. There are eligibility requirements for a Roth IRA so make sure you speak to your tax professional.
If you need help, you can call us at 1-833-829-6472, Monday-Friday from 8 AM to 9 PM and Saturday from 8:30 AM to 5 PM ET. If you have a managed retirement account, please work directly with your J.P. Morgan advisor to convert your account.
You can easily open a Roth IRA online or with a J.P. Morgan advisor. Once you fill out an application and are approved, you’re ready to start making contributions (if eligible) and investing in mutual funds, bonds, stocks and exchange-traded funds (ETFs).
Yes, you can have both a Traditional IRA and a Roth IRA and may contribute to one or both as long as you (or your spouse, if filing jointly) have earned income. Keep in mind that the annual IRA contribution limit is shared across all your IRAs combined (Traditional and Roth), and Roth contributions may be limited by income.
Roth IRA earnings can be withdrawn tax-free only in a qualified distribution—generally when you’re 59½ or older and it’s been at least five tax years since you first opened and funded any Roth IRA. A qualified distribution may still occur if you are under 59½ and have met the five-year tax period. Contact a tax professional for further information.
You generally fund a Roth IRA by contributing earned income (from you or your spouse, if filing jointly), up to the annual IRA contribution limit. Roth IRA contributions may also be limited based on your filing status and income. Use our calculator to check your eligibility.
Eligibility depends on factors such as earned income, age, filing status, and the type of IRA you’re considering. Use our calculator to check your eligibility.