Opening a Trump Account for your older kid or teen: What you need to know
Editorial staff, J.P. Morgan Wealth Management
- Trump Accounts can be opened for older kids and teens with a valid Social Security number (SSN) so long as the account is opened by December 31 of the year they turn 17.
- Children born before 2025 are not eligible for the $1,000 government “seed” money (a pilot program).
- Even without government seed money, there may be advantages for your older child to have a Trump Account as they may qualify for charitable contributions, receive other types of contributions and so they can take advantage of long-term investing to build wealth for their future.

Trump Accounts can be opened for children with a valid Social Security number (SSN) who do not have a prior Trump Account so long as it is opened by December 31 of the year the child turns 17. This includes older kids and teens born before 2025 – the only difference is that these older children are not eligible for the $1,000 government seed deposit; that pilot program is available only to babies born between January 1, 2025, and December 31, 2028, who are U.S. citizens with valid SSNs.
Even without the $1,000 seed deposit from the government, a Trump Account can help older kids and teens take advantage of long-term investing. Here are some things to know before opening a Trump Account for your older kid or teen.
Can you open a Trump Account for an older kid or teen?
Yes, you can open a Trump Account for an older kid or teenager as long as they have a valid SSN and you open the account by December 31 of the year they turn 17. After that deadline, the account cannot receive employer or philanthropic contributions; however, if the account has already been opened, the child can assume ownership upon attaining the applicable age of majority (usually age 18) and make contributions under general traditional IRA rules.
Older kids and teens born before 2025 are not eligible for the $1,000 government seed deposit, which is one of the program’s biggest benefits. But that doesn’t mean parents or guardians of older kids and teens shouldn’t consider opening a Trump Account for their child.
Trump Accounts are tax-advantaged investment accounts for minors, with the goal of helping kids build wealth early. Parents, family members and other individuals can contribute up to $5,000 per year (indexed for inflation after 2027) to a Trump Account during the growth period (defined as ending December 31 of the year the child turns 17).
Employers can also contribute up to $2,500 annually (indexed for inflation after 2027), which counts against the overall $5,000 yearly cap. Charitable organizations, states and other entities can also make contributions to Trump Accounts and those contributions do not count against the annual limit, but they must be “qualified general contributions.” These programs remain limited and may depend on factors like your location or income.
During the growth period, the money in a Trump Account may be invested in broad U.S. equity index funds – such as mutual funds or exchange-traded funds (ETFs) that track a U.S. stock index such as the S&P 500 – that have no leverage and expense ratios of 0.1% or less. As of August 2026, and subject to limited exceptions for cash, no other investments are permitted, including sector-specific funds.
At launch, all contributions to Trump Accounts held at the Treasury-appointed initial trustee will be invested in the State Street SPDR Portfolio S&P 500 ETF (SPYM). In the coming months, the Treasury expects to allow authorized individuals to allocate across four additional ETFs, though timing of their availability is pending as of August 2026. If the Trump Account is rolled over to another Trump Account at a different financial institution, investment options may change.
Who can open a Trump Account for an older kid or teen?
The adult who opens a Trump Account for an older kid or teen is considered the “authorized individual” or “responsible party” for the account until such time as the child/beneficiary assumes control after the growth period. The authorized individual/responsible party must be, in priority order: legal guardian, parent, adult sibling or grandparent of the eligible individual. A child can have only one Trump Account.
When do older kids and teens gain access to their Trump Account funds?
The account is held in the child’s name (they are the beneficial owner), and an authorized individual/responsible party controls the account during the growth period. After the growth period and when the child reaches the applicable age of majority (usually age 18), the child can take control of the account, which then, generally speaking, follows the same rules as a traditional IRA.
Distributions from a Trump Account generally can’t be taken during the growth period. After the growth period, the Trump Account is generally subject to traditional IRA rules regarding contributions, investments, and withdrawals and taxation – including the potential for an early withdrawal tax on distributions taken before age 59½ unless an IRS exception applies.
Learn how Trump Accounts can support your child’s future
Build lasting financial security for your child with a tax-advantaged Trump Account and help them save for retirement and other future goals.
Maximizing a Trump Account for your older child
Opening a Trump Account for an older child may be worthwhile, but it may be wise to have a strategy in place to make the most of this investment vehicle.
One way to do this is by taking advantage of contributions from other individuals and employers (if applicable). Some employers may offer contributions of up to $2,500 per year per employee (indexed for inflation after 2027), which can significantly reduce how much you need to contribute out of pocket. (Employer contributions to your child’s Trump Account that meet certain conditions do not affect your taxable income, but do count toward the overall $5,000 limit.) Family members and other individuals can also play a role by contributing money on birthdays, holidays or other milestones, helping you reach the annual maximum.
Additionally, eligible children in certain ZIP codes and/or who meet other stipulated criteria may qualify for contributions from philanthropic donors or foundations, such as from the Michael & Susan Dell Foundation or Dalio Philanthropies. These contributions are called “qualified general contributions” and are not counted against the $5,000 limit.
Setting up automatic contributions, coordinating with family members and taking advantage of any employer contributions can help you reach the $5,000 contribution limit each year (indexed for inflation after 2027). Since your older kid or teen has a shorter time horizon for their account to grow, making contributions annually can make a big difference in how much money is available to them in the future.
Projected growth of a Trump Account (hypothetical)
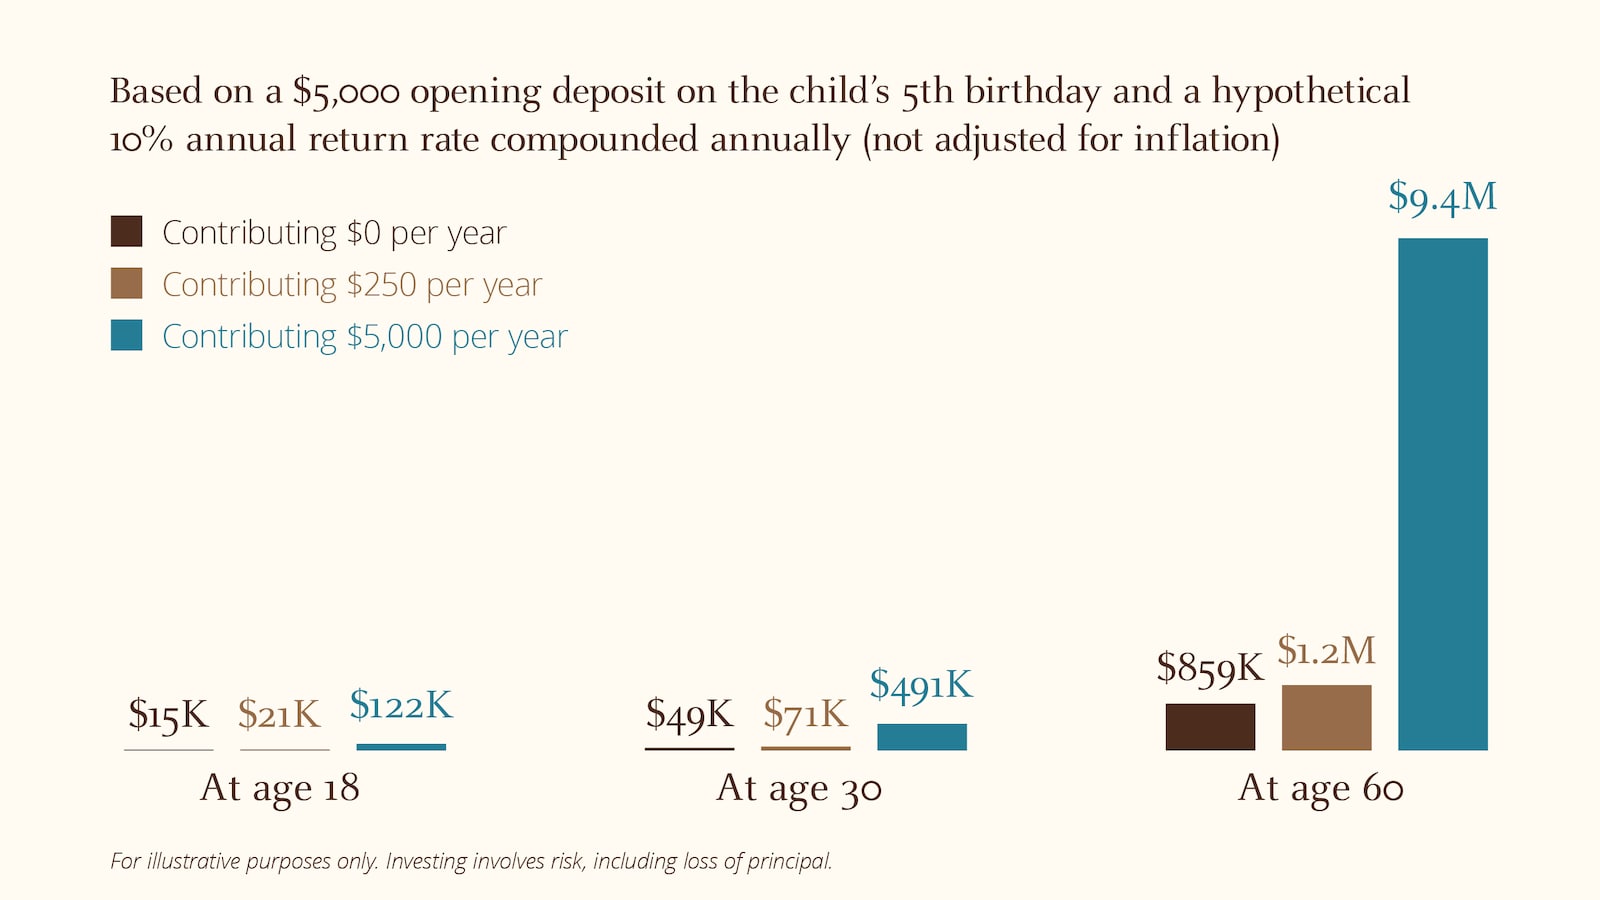
The above is a hypothetical example for illustrative purposes only and should not be relied upon in making an investment decision. These examples do not reflect actual or future performance results of any specific vehicle and are based solely on the hypothetical illustration cited. Assumed starting amount is $5,000 at age 5. Assumed hypothetical annual rate of return is 10%, not adjusted for inflation, and compounded annually. Investing involves risk, including loss of principal.
Practical steps for families with older kids
A Trump Account can help your older kid or teen start investing for their future. Before opening a Trump Account, it’s important to understand eligibility rules and what documents you’ll need, plus how you can manage the account.
- Review your child’s eligibility: Trump Accounts are available to open and fund through December 31 of the year your child turns 17. If they are already 17 years old on January 1 and turn 18 by December 31 of that year, you cannot open a Trump Account for them.
- Gather your documents: To open the account, you’ll need your child’s SSN and some basic personal information like a home address.
- Fill out IRS Form 4547 or sign up on the IRS website: Fill out IRS Form 4547Opens overlay or sign up on the IRS websiteOpens overlay with the adult’s and child’s information. The IRS says Form 4547 can be, but does not have to be, filed with a tax return. Name, SSN, date of birth and home address are all required for both the adult and the child on either form. The adult’s phone number and email address are also required.
- Download the Trump Accounts: Official App: You can download the app from TrumpAccounts.gov or through an app store. You must sign up for a Trump Account before you can use the app. You’ll need the email address you used to sign up for the Trump Account to get into the app. After you create a password and add your phone number in the app, you can sign up for notifications to get updates on your child’s Trump Account.
- Activate the account: Once the information is accepted, the Treasury Department or its agent will send you information via email to finish activating your child’s Trump Account via the app. Keep an eye out for emails from this address: no-reply@TrumpAccounts.Treasury.gov.
Once the Trump Account is opened, and since you may have less overall time to contribute to the account than other parents with younger children, you can consider setting up automatic contributions to help you maximize your annual contributions. If you are considering a move to another financial institution, the Trump Account can be moved via a trustee-to-trustee transfer (also known as a “Trump Account rollover”), but this is only allowed during the growth period and when it is made to another Trump Account for the same beneficiary. The rollover must be a full transfer – partial transfers are not permitted. The trustee-to-trustee transfer is a non-taxable event.
The bottom line
You can open a Trump Account for older kids or teens, but they can’t receive the $1,000 seed money if they were not born between 2025 and 2028. However, they may be eligible for charitable contributions, and a Trump Account can still help your child get a head start on building their wealth even if you can’t contribute the maximum each year. Before getting started, it’s important to know that you must open a Trump Account no later than December 31 of the year the child turns 17. After that, Trump Accounts cannot be opened. However, if the account is opened by then, the rules for contributions, distributions and investing change and the account will generally function as a traditional IRA in the child’s name. By setting up a Trump Account in their youth, your child may be able to take advantage of one more tax-advantaged investment account to help with education, expenses, homeownership or a host of other financial goals, including retirement. Distributions after the growth period are subject to ordinary income tax and potential early withdrawal tax.
Invest your way
Not working with us yet? Find a J.P. Morgan Advisor or explore ways to invest online.